

Key takeaways
The SEC approved spot Bitcoin ETFs in January 2024, and trading began the next day. This post was written before that decision, and the update below reflects what actually happened.
The real change was access. Advisors, retirement accounts, and institutions that were never able to hold Bitcoin directly could suddenly buy it in a familiar wrapper.
A spot ETF holds Bitcoin. A futures ETF holds contracts. That difference shows up in tracking and in cost.
What the ETF did not solve: you do not hold keys, you cannot self-custody, and shares sit squarely inside the wash sale rule that direct coins currently sidestep.
For a large private holder, the ETF is a useful instrument alongside direct ownership rather than a replacement for it.
When this was first written, the spot Bitcoin ETF was still a pending question. It has since been answered, so here is the updated version: what the approval changed, what it did not, and what it means if you already hold Bitcoin directly.
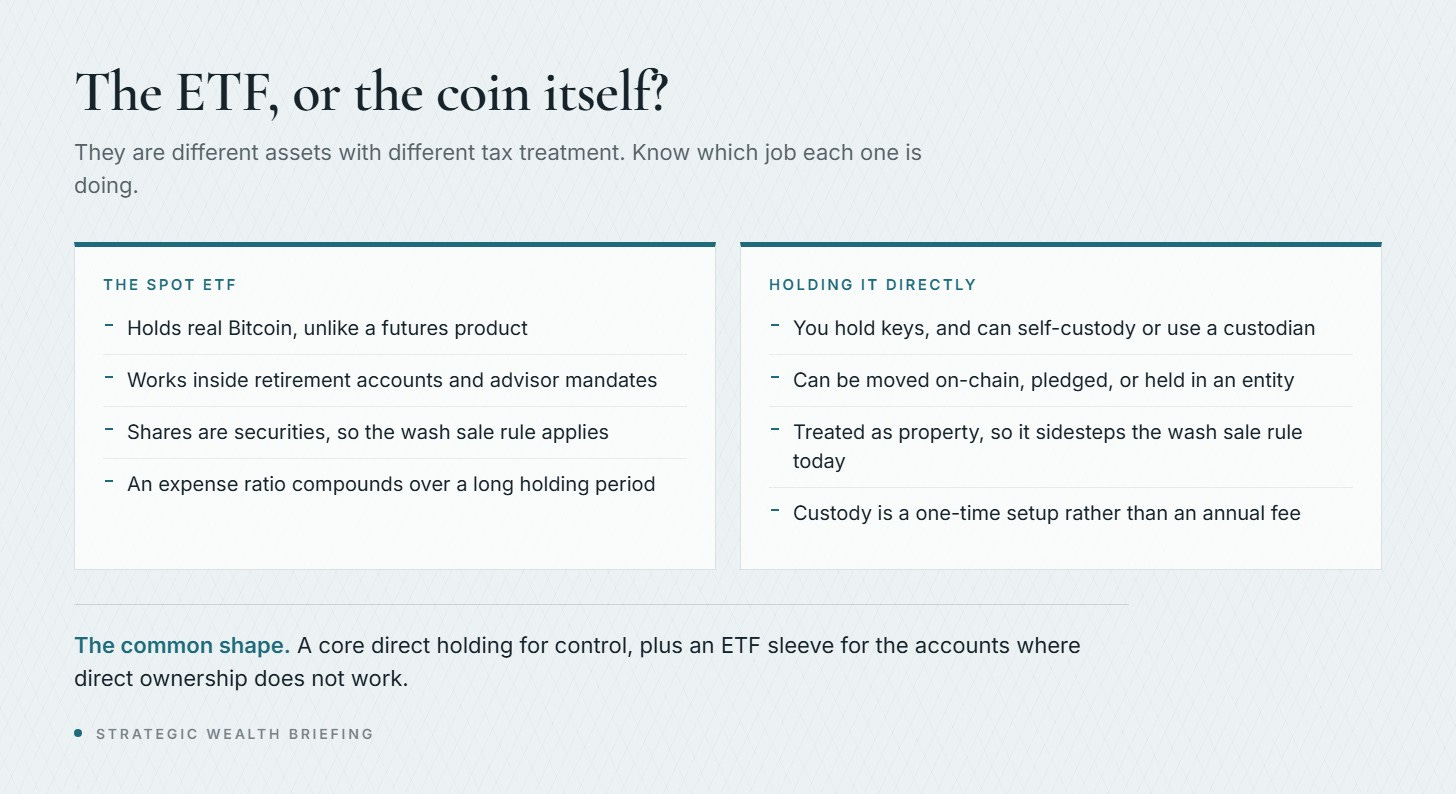
What the Bitcoin spot ETF actually changed, and the two things it does not do for a direct holder.
What actually happened?
The SEC approved spot Bitcoin exchange-traded products in January 2024, and the funds began trading immediately after. That ended roughly a decade of rejected applications.
The significance was never really about the product design. It was about who could now participate. A registered advisor with a compliance department, a retirement platform with an approved-product list, or an institution with a custody policy could not touch Bitcoin directly. They could buy an ETF.
What is the difference between a spot ETF and a futures ETF?
A spot ETF holds actual Bitcoin. The fund buys the asset, a custodian holds it, and the share price tracks the underlying reasonably closely.
A futures ETF holds contracts on Bitcoin's future price. It never holds the coin. Contracts expire and get rolled forward, and that rolling has a cost that shows up as tracking drift over time.
Futures products existed years before the spot version was approved, which is why the spot approval mattered so much. It removed a structural cost and gave holders exposure to the asset rather than to a chain of contracts about it.
What did the ETF actually change?
Three things, in order of how much they matter.
Access. This is the whole story. Money that was structurally locked out could finally participate through an instrument its compliance function already understood.
Legitimacy by plumbing. Once an asset trades through the same rails as everything else in a portfolio, the conversation with a committee changes. The argument becomes allocation size rather than whether it is permitted at all.
Price discovery and liquidity. More participants, tighter spreads, and a reference price that traditional systems can consume.
What did it not change?
Quite a lot, and this is where large private holders should pay attention.
You do not hold keys. An ETF share is a claim on a fund that holds Bitcoin. That is a different asset from Bitcoin. If self-custody is the point for you, the ETF does not deliver it.
You cannot move it on-chain. No self-custody, no direct transfer, no using it as collateral the way you might with a coin you actually hold.
**The wash sale rule applies.** This catches people. ETF shares are securities, so selling at a loss and rebuying inside the 30-day window disallows the loss. A direct holding of Bitcoin is treated as property rather than a security, and under current law does not get caught the same way. So the tax-loss harvesting flexibility that direct holders enjoy does not carry over to the fund.
Fees are ongoing. Small annual expense ratios compound over a long holding period in a way a one-time custody setup does not.
How should a large holder think about it?
Usually as one instrument among several rather than a replacement.
A few places the ETF genuinely fits:
Inside a retirement account, where holding the coin directly is either impossible or awkward.
For a portion you want liquid and simple, particularly if heirs would find a brokerage account far easier to inherit than a wallet.
Where an institution or advisor mandate requires a registered product.
And places it does not:
The core long-term position, if control and self-custody are why you own it.
Anywhere you want to harvest losses aggressively, given the wash sale treatment.
Any use requiring the asset on-chain, such as collateral or direct transfer.
A common shape is a core direct holding in real custody, with an ETF sleeve for the accounts and situations where direct ownership does not work.
A quick FAQ
Is a spot Bitcoin ETF safer than holding Bitcoin? It removes key risk and adds counterparty and fund risk. Different risks, not fewer.
Can I hold one in an IRA? Generally yes, which is a large part of why the approval mattered.
Does the ETF affect the Bitcoin price? It changed who can buy and how easily. Attributing specific price moves to it is guesswork.
Should I sell my direct Bitcoin and buy the ETF? That would be a taxable sale, and it would give up self-custody and the current wash sale treatment. Run it past a CPA before assuming the wrapper is an upgrade.
The short version
The spot ETF opened Bitcoin to a lot of money that was previously locked out, and it did so through a wrapper the traditional system already knew how to hold.
For someone building a long-term position with control, it sits beside direct ownership rather than replacing it. Know which job each one is doing, and do not assume the convenient version carries the same tax treatment.
XRP!