

Key takeaways
Build the smallest version that solves your actual problem. Almost every family office that disappoints was overbuilt on day one.
The first hire is a coordinator, not an investor. The gap in most wealthy families is nobody owning the space between the professionals.
Choose the model before the staff: single, multi-family, or virtual. They cost very different amounts and suit very different situations.
Governance is the piece families postpone, and it is the piece that decides whether any of it survives the founder.
Expect to rebuild it. What fits your family now will not fit in ten years, and planning for revision beats planning for permanence.
There is an old line that if you have seen one family office, you have seen one family office. It is true, and it is also unhelpful when you are trying to decide what to build.
Here is the order the pieces usually go in, and the mistakes that cost the most.
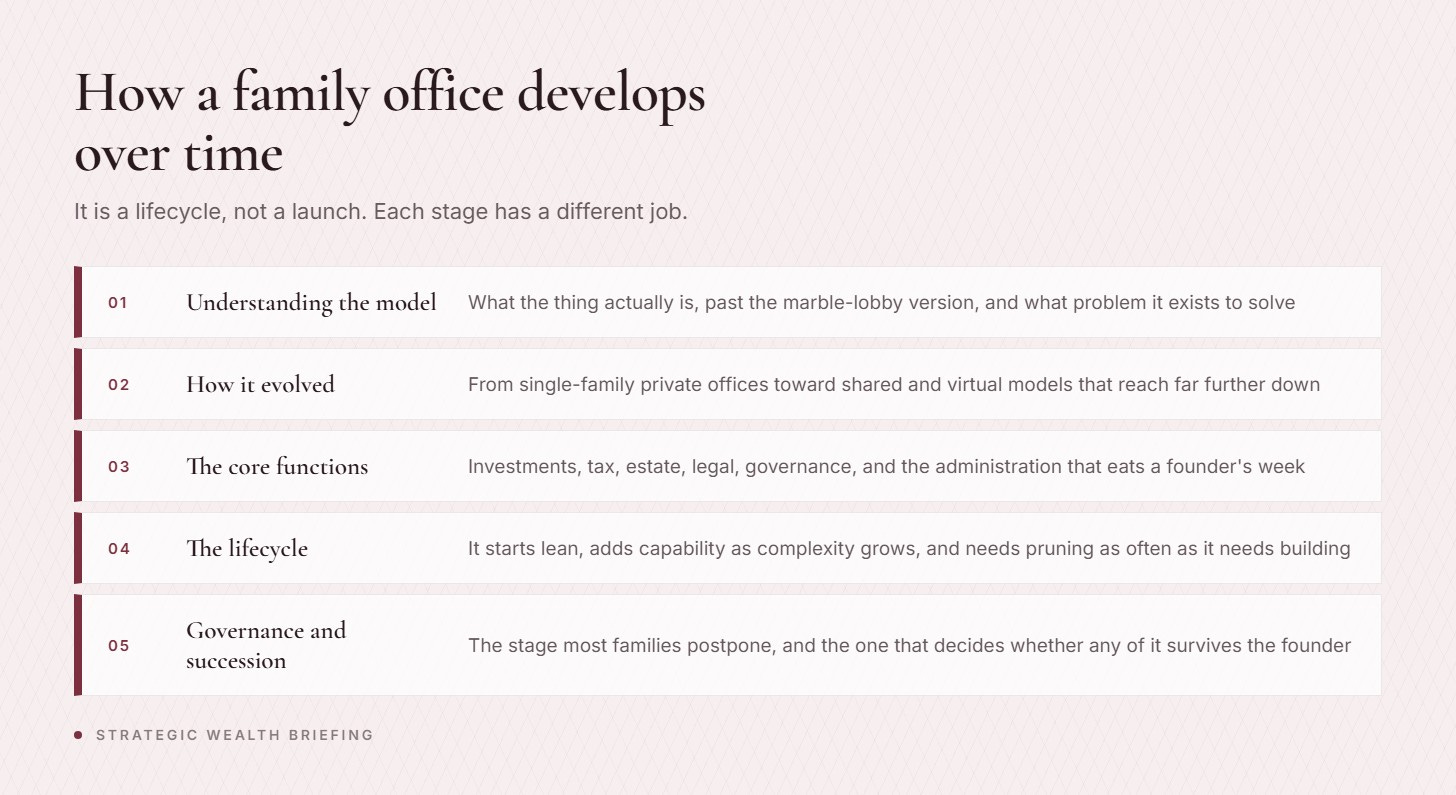
How to set up a family office: the stages it moves through, and the one most families postpone.
What problem are you actually solving?
Start here, because the answer determines everything else.
Most families arriving at this question do not lack advisors. They have a CPA, an attorney, an advisor, maybe a banker, and all of them are competent. What they lack is anyone whose job is making those people work together, and anyone who can see the whole picture at once.
If that is your problem, you need coordination, and coordination is cheap relative to a staffed office.
If your problem is different, say you need dedicated investment management of a nine-figure balance sheet with direct deals and an in-house team, that is a different build with a different cost.
Naming the problem precisely prevents the most expensive error in this whole area, which is building the impressive version rather than the useful one.
Which model fits?
Three real options, and the gap between them is enormous.
A single family office is a private company serving one family, with its own employees. It offers the most control and customization. It is also a multimillion-dollar annual commitment, commonly quoted at roughly 1% to 2% of assets a year, which is why it rarely makes sense below nine figures.
A multi-family office shares one team and platform across many families. You get institutional service without funding the office. Families roughly in the $25 million to $250 million range often land here. It is generally a registered investment adviser, which brings oversight and a fiduciary standard.
A virtual family office is a lead coordinator plus a vetted bench of outside specialists: estate attorney, tax team, investment managers, custodian, bookkeeper. You get the function, integrated oversight, without the fixed cost of employees. It tends to fit from roughly $5 million to $50 million.
Most families who think they want the first one are better served by the third.
Who do you hire first?
The coordinator, and this surprises people who expected the answer to be an investment professional.
Investment management is the easiest capability to buy well from outside. Coordination is the hardest, and it is the thing nobody currently owns. Someone has to hold the whole picture, chase the loose ends, make the specialists talk, and notice when a document no longer matches reality.
After that, hire against the gaps you actually have rather than a template. A family with a coming liquidity event needs tax capacity first. A family with heirs in three states needs estate capacity first. There is no standard second hire.
What does the office actually need to do?
Five functions, in roughly the order they matter:
Coordination. Making the professionals operate as one team, which is the whole reason the model exists.
Reporting. One picture of everything, across every entity and custodian. Sounds administrative, changes every conversation.
Tax and estate upkeep. Planning through the year, and keeping documents matching what the family owns as that drifts.
Investment oversight. Allocation and manager selection, whether performed in-house or supervised.
Administration. Property, insurance, bill pay, the paperwork. Unglamorous, and it is what gives a founder their week back.
Why is governance the piece that decides everything?
Because without it the office serves whoever is loudest, and it does not survive the founder.
Governance means writing down how decisions get made: who has a vote, who speaks for the family, what happens when people disagree, and how the next generation gets involved. It is the layer that turns a service arrangement into something durable.
Families postpone it because it feels premature and because the conversations are uncomfortable. It gets built after a crisis in most cases, which is the most expensive time to build anything.
What goes wrong most often?
Four things, repeatedly.
Overbuilding. Hiring staff and taking office space for a balance sheet a virtual model could have run. Expensive, hard to unwind, and the second most common regret.
No clear mandate. The team is not told what to optimize for, so each professional applies their own defaults and those defaults conflict.
Never revisiting. Structures drift out of date. A family office needs pruning as often as it needs building.
Treating it as an investment shop. If performance is the only measure, the coordination work that justifies the model goes unmeasured and eventually unfunded.
A quick FAQ
How much do I need before this makes sense? For a staffed single family office, realistically nine figures. For a virtual model, the low millions, and complexity matters more than the balance.
Can I start small and grow? Yes, and that is usually the right approach. Start with coordination, add capability as complexity genuinely demands it.
Do I need an office? No. Most of what a family office does is coordination and reporting, neither of which requires a building.
How long does it take to set up? A virtual arrangement can be working within a quarter. A staffed office is a year-long project before it runs properly.
The short version
Name the problem, pick the smallest model that solves it, hire a coordinator before an investor, and write down how decisions get made.
Then expect to revise it. The families who do well here treat this as a structure that evolves, not a monument they finish.
So I just got this post via email.
I absolutely 100% never subscribed.
Where did you get my email and how did you subscribe me - not cool.