

Key takeaways
Rule 506(b) lets you raise from an unlimited number of accredited investors, plus up to 35 sophisticated non-accredited ones, without SEC registration.
The trade is that you cannot advertise. No general solicitation, which means no public posts, no cold outreach, no pitching a room you were invited to speak at.
The workaround is a substantive pre-existing relationship, and both words carry weight. Substantive means you know their financial situation. Pre-existing means before this offering existed.
Documentation is what proves it. A dated record of when and how each relationship began, and what you knew about their sophistication.
If you need to raise publicly, 506(c) exists and permits advertising, at the cost of verifying every investor's accreditation.
This comes up constantly with people using our SPV platform, and it is the rule most likely to be broken by accident. Here is what a substantive pre-existing relationship actually means and how you evidence one.
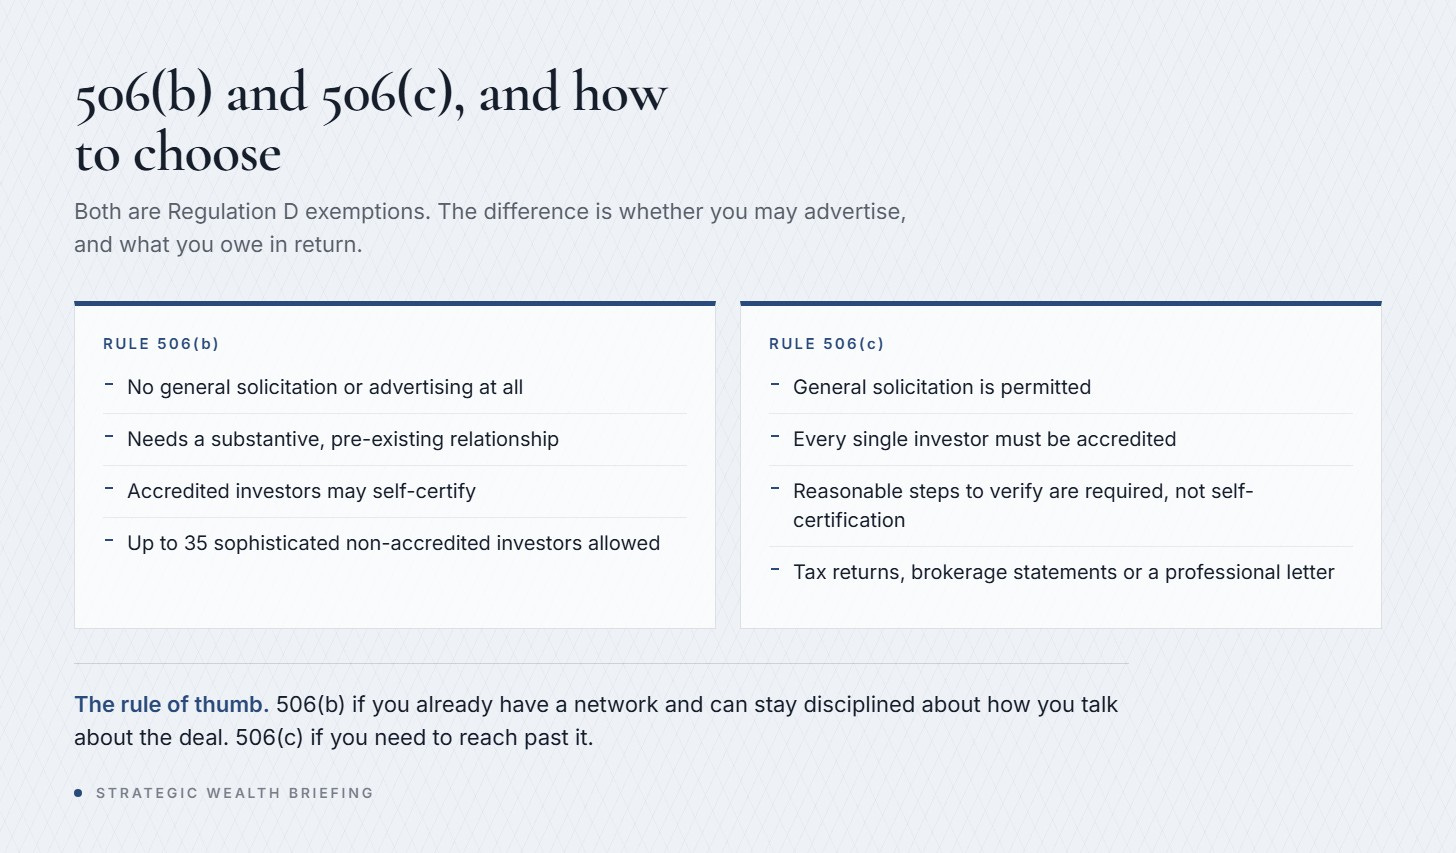
506(b) against 506(c). The rule you pick decides whether you can market the offering and how much verification work you take on.
What does 506(b) allow?
Quite a lot, which is why it is the most used private offering exemption.
Under Rule 506(b) you can raise an unlimited amount, from an unlimited number of accredited investors, plus up to 35 non-accredited but sophisticated investors, without registering the offering with the SEC.
The condition attached is the one that trips people: no general solicitation or advertising. You cannot post about the raise publicly, email a purchased list, or pitch it from a stage. If the offering reached someone through a public channel, you have likely blown the exemption for the entire raise, not just that investor.
What makes a relationship "substantive"?
Knowing enough about the person to assess whether the investment is suitable for them.
That means you have information about their financial circumstances and their sophistication. Not their name and a handshake. Not a LinkedIn connection. Something that would let you form a genuine view on whether they can evaluate and bear the risk.
In practice, substantive usually means you have had real conversations covering their investment experience, their financial position, and their objectives, and you have a record of it.
What does not count: a business card, a mutual follow, an introduction at a conference last month, or a mailing list they joined from your website.
What makes it "pre-existing"?
The relationship existed before the offering did.
This is the part people underestimate. Meeting someone, having a substantive conversation about their finances, and then telling them about a deal you are already raising for does not satisfy it. The relationship has to predate the offering, because the whole point is that the deal did not come to them through a solicitation.
There is no bright-line waiting period in the rule. What matters is that the sequence is defensible: relationship first, offering second, with a clear gap and a record of both.
How do you actually document it?
This is the part that saves you, and it is unglamorous.
Keep a record, per investor, showing:
When the relationship began, with a date and how it started.
What you learned about them, covering financial circumstances and investment sophistication.
When the conversation happened relative to when the offering was formed.
How they were contacted about the offering, and through what channel.
A common approach is an investor questionnaire completed at the point the relationship forms rather than at the point of the raise, plus dated notes of substantive conversations. If a regulator ever asks, that file is the answer. Recollection is not.
What about 506(c)?
The alternative, and it solves the opposite problem.
Rule 506(c) permits general solicitation. You can advertise, post publicly, and talk about the raise openly. Two conditions come with it:
Every investor must be accredited. No non-accredited participants at all.
You must take reasonable steps to verify accreditation. Not self-certification. Documents: tax returns, brokerage statements, or a written confirmation from their CPA, attorney or a registered broker-dealer.
That verification burden is real work, and some investors decline to provide the documentation. That is the trade for being able to advertise.
Which should you use?
A reasonable rule of thumb.
506(b) if you already have a network. Less friction, investors can self-certify, and you can include a limited number of sophisticated non-accredited people. You just cannot market.
506(c) if you need to reach beyond your existing network. You can market freely, and you accept the verification workload.
Most sponsors with an established investor base use 506(b) and stay disciplined about how the deal reaches people. Most first-time sponsors without a network find they need 506(c), and are surprised by the verification step.
A quick FAQ
Can I post about my raise on social media under 506(b)? No. That is general solicitation, and it can disqualify the exemption for the whole offering.
Can I talk about my business publicly while raising? Generally yes, provided you are not marketing the offering itself. The line is fact-specific and worth running past securities counsel.
How long does a relationship need to exist first? There is no stated period. The sequence and the documentation matter more than the calendar.
What happens if I get it wrong? Potentially rescission rights for investors and regulatory exposure. This is the part worth spending money on getting right in advance.
The short version
506(b) lets you raise privately from people you already know, and the exemption rests on relationships that were both substantive and pre-existing.
Document how and when each relationship began, before there is a deal to point at. If your network is not deep enough to fund the raise, use 506(c) and budget for verification rather than stretching the definition of a relationship you do not really have.
The detail of these things always amazes me - very well done